Car Insurance in India: Comprehensive vs Third-Party and Useful Add-ons
Understand third-party versus comprehensive car insurance in India, IDV, no-claim bonus and which add-on covers are actually worth buying.
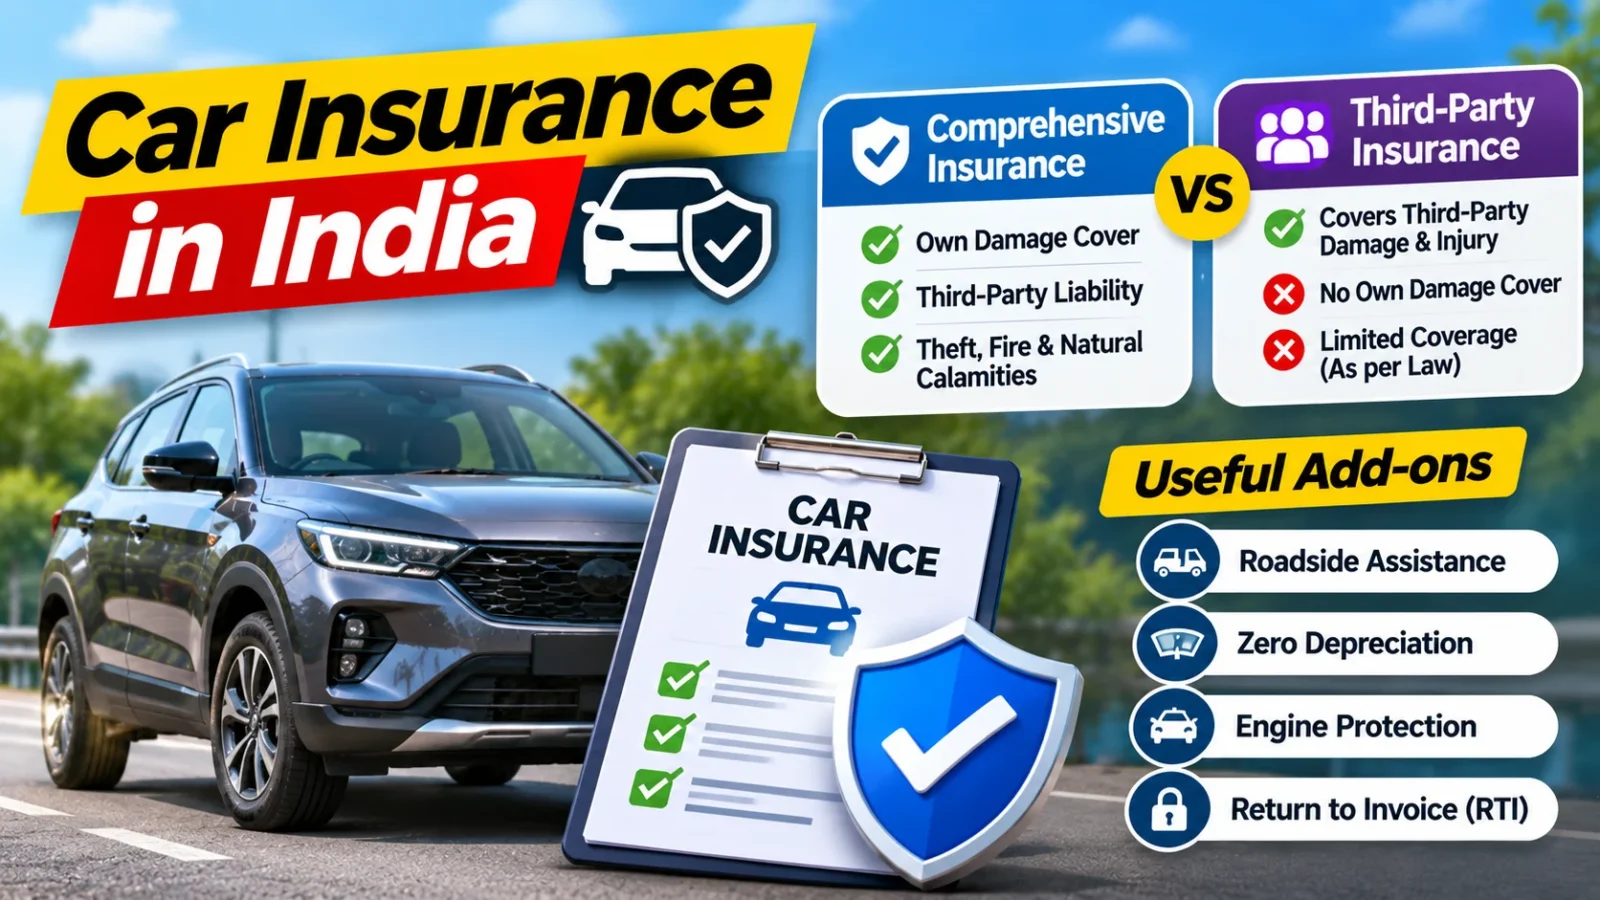
Car Insurance in India:- Car insurance is mandatory in India, but choosing the right cover matters. Here is a plain-language guide to your options.
Third-party insurance
Third-party cover is required by law. It covers your legal liability for injury, death or property damage to other people caused by your car. It does not pay for damage to your own car.
Comprehensive insurance
This combines third-party liability with own-damage cover for your car, which typically protects against accidents, theft, fire, natural calamities and man-made events. It costs more but gives much broader protection, so it is the sensible choice for most owners, especially for newer cars.
Key terms you should know
- IDV (Insured Declared Value): the car’s insured market value, which is the maximum payout for a total loss or theft. It reduces as the car ages. Setting it too low reduces your claim; setting it unrealistically high does not help.
- No-claim bonus (NCB): a discount on the own-damage premium for each claim-free year, rising in slabs up to a maximum of 50 percent. It usually belongs to you, not the car, so you can carry it to a new policy or a new car.
- Deductible or excess: the part of a claim you pay yourself.
- Cashless garage network: garages where the insurer pays the workshop directly.
Add-on covers worth considering
| Add-on | What it does | Who needs it |
|---|---|---|
| Zero depreciation | Pays for replaced parts without deducting depreciation | Newer cars |
| Engine protection | Covers engine damage from water ingression or oil leakage | Flood-prone areas |
| Return to invoice | Pays the invoice value if the car is stolen or written off | New cars |
| Roadside assistance | Towing, battery jump-start, flat tyre | Frequent travellers |
| Consumables cover | Pays for nuts, oils, coolant used in repair | Optional |
| NCB protection | Keeps your bonus after a claim | Careful drivers who expect a small claim |
Engine protection is especially relevant if you live somewhere that floods; see our monsoon checklist and driving in flooded roads.
How to choose an insurer
- Compare premiums and coverage across several insurers.
- Look at the claim settlement record, garage network and customer service reviews.
- Read what is excluded, such as driving without a valid licence, drunk driving or wear and tear.
- Do not choose purely on price. The cheapest policy may have the weakest cover.
Making a claim
- Inform the insurer promptly.
- Take photos, and file a police report for theft or major accidents.
- Do not move the car in a major accident without guidance.
- Keep documents ready: policy, RC, driving licence and repair estimates.
Save money legally
- Renew on time. A lapse can cost you the NCB and trigger an inspection.
- Avoid tiny claims that cost you the NCB.
- Choose a sensible voluntary deductible.
- Install safety features that may qualify for discounts.
Electric cars
EV policies may include battery and charger cover. Check what is included. See EV battery life and warranty.
Frequently asked questions
Can I buy only third-party for an old car?
Yes, but you lose own-damage cover.
Do I need valid insurance to sell the car?
See documents needed to buy or sell a car.
Insurance rules and products change. Confirm details with the insurer and the regulator’s guidance.

Related articles
Documents Needed to Buy or Sell a Car in India
A practical checklist of the documents and forms needed to buy or sell a car in India, including RC transfer, insurance and…
Car Resale Value: What Affects It and How to Get a Better Price
What decides your car's resale value, and how can you get a better price? Learn the key factors and a step-by-step plan…
How to Calculate Your Car’s True Monthly Running Cost
Find out what your car really costs each month. Use this simple framework covering fuel, EMI, insurance, servicing, tyres and depreciation.
0 comments